On this page
You can make money from your home by renting a room or unit to a long-term tenant, renting to short-term guests, or renting space for storage, a business, an event or a film shoot. You can also borrow against your equity, but that is a loan you repay, not income. Rent from a home you live in is generally taxable (with a small exception for very short rentals), and your mortgage, your HOA and your city can all limit what you do.
This guide orders the options by how much of your home they use and how much they touch your loan. No one can promise an income figure, because rents depend on your market, your space and local rules.
Ways to make money from your home
Here are the options, starting with the ones that usually take the most space and bring the most loan, HOA and tax questions:
- A room or the whole house, rented to a long-term roommate, a tenant or a traveling worker.
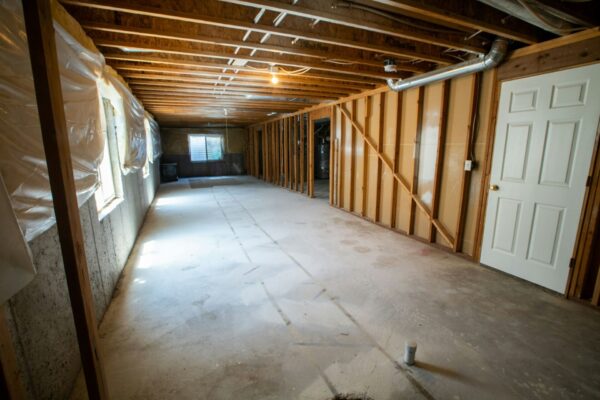
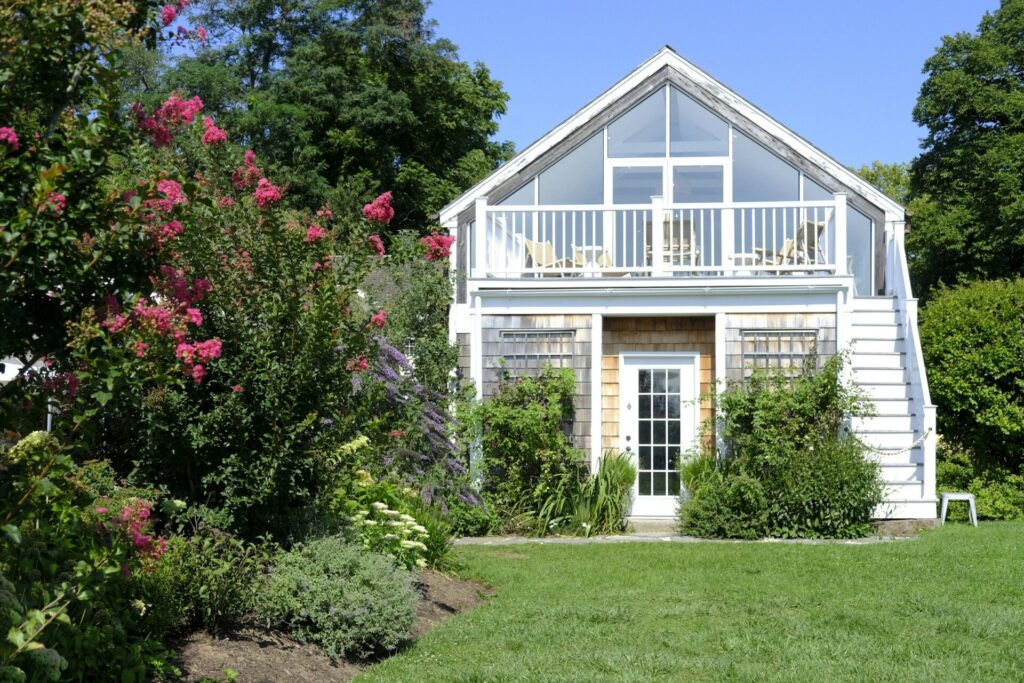
- An ADU, such as a garage apartment, a basement unit or a backyard cottage.
- Short-term stays for guests who book through a site like Airbnb or Vrbo.
- Storage space in a garage, basement or spare room.
- A business or home office in space you already pay for.
- Film or photo shoots in your home or yard.
- Events such as showers, rehearsal dinners or meetings.
- Produce from your garden.
The first three use the most of your home and bring the most rules, because tenants or guests live there. The smaller ideas carry fewer loan issues, although zoning and insurance still apply.
Rent a room or the whole house
Renting a room in your house is the simplest way to make money from your home with space you already have. The renter could be a long-term roommate, a student or a traveling professional, such as a nurse on a temporary assignment who wants a furnished room.
Renting the whole house is a bigger step, because you have to move out. Before you take that on, read up on the duties of becoming a landlord. And if you are still shopping for a home, buying a duplex or fourplex to live in one unit is another way to earn rent from the start.
What renting does to your mortgage
Renting a room while you keep living in the home does not change your loan. Renting out the whole house can, especially soon after you buy.
Most mortgages on a primary home include an occupancy promise. Under the Fannie Mae Selling Guide, the borrower must move in within 60 days of signing the mortgage and live there for at least one year. The FHA handbook also requires you to move in within 60 days and to intend to stay at least one year. So, if you move out and rent the whole home within that first year, you could break your loan terms. Check your mortgage documents and ask your servicer before you sign a lease.
Does a roommate’s rent help you qualify for a new loan
Usually not. Fannie Mae generally does not count boarder income from your own home as stable income, apart from narrow exceptions. FHA can count it, but only if you have a 12-month history of boarder income and still receive it, and it is capped at 30% of the income used to qualify.
Taxes on room rent
Room rent is taxable income. Under IRS Publication 527, you split shared costs, such as mortgage interest and utilities, between the rented part and your part. For example, the IRS shows a 180-square-foot room in a 1,800-square-foot house, so 10% of shared costs go to the rental. Costs that belong only to the rented room, such as painting it, count in full as rental expenses.
If you plan to refinance or buy and want to see how a lender would treat your income, compare quotes from a few lenders.
Rent out an ADU on your property
An accessory dwelling unit (ADU) is a separate, smaller living space on the same lot as your house. Lenders use a specific test for what counts as an ADU. Under Fannie Mae Selling Guide B2-3-04, an ADU has its own entrance, kitchen, sleeping area, bathing area and bathroom. It must also be smaller than the main home, and only one is allowed per lot. Fannie Mae’s examples include a unit over a garage, a basement apartment and a small addition. An ADU can also be a detached unit.
For the kitchen, Fannie Mae requires at least cabinets, a countertop, a sink with running water and a stove or a stove hookup. A hot plate or microwave does not count.
ADU rent can help you qualify, with caps
An ADU is one of the few ways to make money from your home that a lender may count. Fannie Mae allows rent from one existing ADU on a one-unit primary home, but only on a purchase or a limited cash-out refinance. FHA also allows it, except on a cash-out refinance. Without a rental history, both generally count 75% of the rent, backed by an appraiser’s rent schedule. In both programs, ADU rent can make up no more than 30% of the income used to qualify. FHA also requires reserves equal to two months of PITI (principal, interest, taxes and insurance) when ADU rent is used.
Zoning and permits come first
Whether you can build or rent an ADU is a local question. Some cities allow detached ADUs and some do not. Many require a permit, and some require the owner to live on the property. Construction costs vary widely, so get local bids first.
Start with your city or county planning department’s ADU page. If an existing unit was built without approval, ask about it before you rent. Fannie Mae can still accept a home with an ADU that zoning does not allow, but only if the lender confirms it will not put a future insurance claim at risk and the appraisal meets Fannie Mae’s rules. FHA expects the ADU to comply with zoning.
Rent your home short term
Short-term rental usually means stays of fewer than 30 days, booked on sites like Airbnb or Vrbo. It can earn during busy times, such as a festival weekend, without a year-round tenant. However, it often carries more rules than the other options here.
Local rules, HOA rules and insurance
Some cities require a short-term rental license or registration, and some cap the number of nights you can rent. Likewise, some HOAs and condo boards ban short-term rentals outright. A standard homeowners policy may not cover paying guests, so ask your insurer what coverage you need before your first booking.
How the IRS treats a home you also live in
The IRS counts a home as your residence if you use it personally for more than the greater of 14 days or 10% of the days you rent it at a fair price. In that case, your rental deductions can be limited, so a rental loss may not be fully deductible. Personal days include days used by family (unless they pay a fair rent and live there as their main home) and by anyone paying less than a fair rent.
There is also a small exception. Under IRS Topic 415, “There’s a special rule if you use a dwelling unit as a residence and rent it for fewer than 15 days. In this case, don’t report any of the rental income and don’t deduct any expenses as rental expenses.” Beyond that, if you give hotel-style services such as regular cleaning or fresh linens, Publication 527 says the income goes on Schedule C, and self-employment tax may apply.
Short-term rent and your mortgage
Short-term rent rarely helps you qualify for the home you live in. Under Fannie Mae Selling Guide B3-3.8-03, a lender counts short-term rent only on a one-unit investment property that is legally allowed to operate as a short-term rental, and it counts only part of that rent.
Before you list, check five things: city rules, HOA rules, insurance, your mortgage’s occupancy terms and how the IRS will treat the income.
Smaller ways to make money from your home
These ideas use less of your home, often space that sits empty. For each one, check zoning, permits and insurance first.
Lease storage space
A dry garage bay, basement corner or spare room can hold someone else’s belongings. Storage rents vary by city, so look at what local facilities charge for a unit about your size.
Run a business or a home office
A spare room can house your business or replace paid office space. Some areas limit home businesses that bring in customers, signs or employees. Also, ask your insurer whether your policy covers business equipment and visitors.
Rent your home or yard to a film or photo shoot
Production companies rent homes and other properties for film, TV, ad and photo shoots. You can list a property on location marketplaces or with a state film office. For example, the California Film Commission runs a location database for property owners. Its guidelines say it does not accept homes that are currently for sale or for rent.
Host events
A large living room or garden can host showers, meetings or small parties. Sites such as Peerspace list spaces by the hour. Before you book anyone, ask your city about event permits and parking, and ask your insurer about guest injuries.
Sell produce
A garden can supply fruit, vegetables or flowers for a farmers market or a roadside stand. Rules for selling food, and for processed items such as jams, differ by state and county. Check local rules before you sell.
Get money out of your house without selling it
Borrowing does not make money from your home. It gives you cash now that you repay later, and each option below uses your home as security. If you do not repay a home equity loan or line of credit as agreed, you could lose the house.
- HELOC: a home equity line of credit lets you draw as needed and repay over time.
- Home equity loan: a lump sum at a set payment. See HELOC vs home equity loan to pick between the two.
- Cash-out refinance: a new, larger first mortgage that pays off the old one. Compare it in cash-out refinance vs HELOC.
- Reverse mortgage: for owners 62 and older, the HECM program pays out equity with no required monthly mortgage payment. See reverse mortgages for seniors.
- Home equity investment: an investor gives you cash now for a share of your home’s future value, typically with no monthly payment. See how a home equity investment works.
Before you borrow, ask how you will repay it, what it costs in total and what happens if your income drops.
Taxes when you make money from your home
Rental income is cash or the fair market value of property or services you receive for the use of your home. Under IRS Topic 414, you generally report it on Schedule E. Advance rent counts as income when you receive it. A security deposit you may have to return is not income. A part you keep generally is.
Track rental days and personal days, and save receipts for shared and rental-only costs. IRS Publication 527 explains how to split those costs. Also, the fewer-than-15-days rule applies only when the home is also your residence.
Before you make money from your home, ask a tax professional how much of the new income will go to taxes. They can also explain what renting part of your home does to your gain when you sell.
If you plan to borrow against your home instead, compare offers from more than one lender first.
FAQ
How can I make money from my house without selling it?
You can make money from your home by renting a room, the whole house, an ADU or short-term stays. Smaller options include storage, a home business, film shoots, events and produce. Borrowing against your equity is also possible, but that is a loan, not income.
Can I rent out a room and still have a mortgage?
Usually yes, as long as you keep living in the home. Renting out the whole house is different. Conventional (Fannie Mae) and FHA loans expect you to move in within 60 days and stay at least a year. VA loans require you to certify that you intend to live there as your home, normally within 60 days of closing. USDA loans require you to live there as your main home for the life of the loan. Check your loan terms and ask your servicer first.
Does rent from an ADU count toward my mortgage income?
It can. Fannie Mae and FHA both allow ADU rent on a purchase or certain refinances, backed by an appraiser’s rent schedule. The ADU rent can make up no more than 30% of the income used to qualify.
Do I pay taxes on rental income from my home?
Generally, yes. The IRS has one exception: if you use the home as a residence and rent it for fewer than 15 days in a year, you do not report that income. In that case, you also cannot deduct rental expenses.
What is the best way to get money out of my house without selling?
The usual options are a HELOC, a home equity loan, a cash-out refinance, a reverse mortgage (62 and older) or a home equity investment. Each is a form of borrowing or selling a share of future value. The right one depends on your age, your equity and how you plan to repay.