On this page
- Do houses under $50,000 still exist?
- Where to find houses under $50,000
- What a $50,000 house usually comes with
- Can you get a mortgage for a $50,000 house?
- What the payment on a $50,000 house can look like
- Are houses under $50,000 a good idea?
- FAQ about houses under $50,000
- Next steps for buying a $50K house
Yes, houses under $50,000 still sell, but they are a small share of the market. Most are in low-cost rural areas and older Midwest and Southern cities. Most also need repairs, are manufactured homes or sell for cash. For scale, the median existing home sold for $417,500 in September 2026, according to the National Association of Realtors (NAR).
A $50K house can still work for a buyer on a tight budget or a small investor. This guide covers where these homes are, what condition to expect, and how a small mortgage loan works.
Do houses under $50,000 still exist?
They do, though in limited numbers. In the Census Bureau’s 2025 American Community Survey (ACS), about 4.1 million of 87.5 million owner-occupied homes were valued under $50,000. That is about 4.7%, or roughly one home in 21.
Keep in mind that ACS values are owners’ own estimates, not sale prices. The count also includes manufactured (mobile) homes, and it covers homes people live in, not homes for sale.
For listings, NAR counted 1.60 million existing homes for sale in September 2026, a 4.8-month supply. It does not report how many are houses under $50,000, so a listing site’s price filter is the best way to check your area.
States with the highest share of homes valued under $50,000
| State | Owner-occupied homes valued under $50,000 (2025) | Share of owner-occupied homes |
|---|---|---|
| Mississippi | 111,000 | 13.0% |
| West Virginia | 69,000 | 12.3% |
| Kentucky | 118,000 | 9.1% |
| Arkansas | 78,000 | 9.1% |
| Louisiana | 112,000 | 8.9% |
| Alabama | 127,000 | 8.7% |
| New Mexico | 50,000 | 8.2% |
| United States | 4,146,000 | 4.7% |
Source: U.S. Census Bureau, 2025 ACS 1-year estimates, table B25075. Counts are rounded, and each estimate has a margin of error.
Texas had about 379,000 such homes in 2025, the most of any state, but that was only 5.2% of its owner-occupied homes.
If you plan to finance a low-priced home, talk to lenders before you shop, because not every lender makes small loans.
Where to find houses under $50,000
Where houses under $50,000 cluster
Low prices cluster in small towns, rural counties and parts of some older industrial cities. In pricier metro areas, the few listings at this level are often manufactured homes or properties with major problems.
The property types
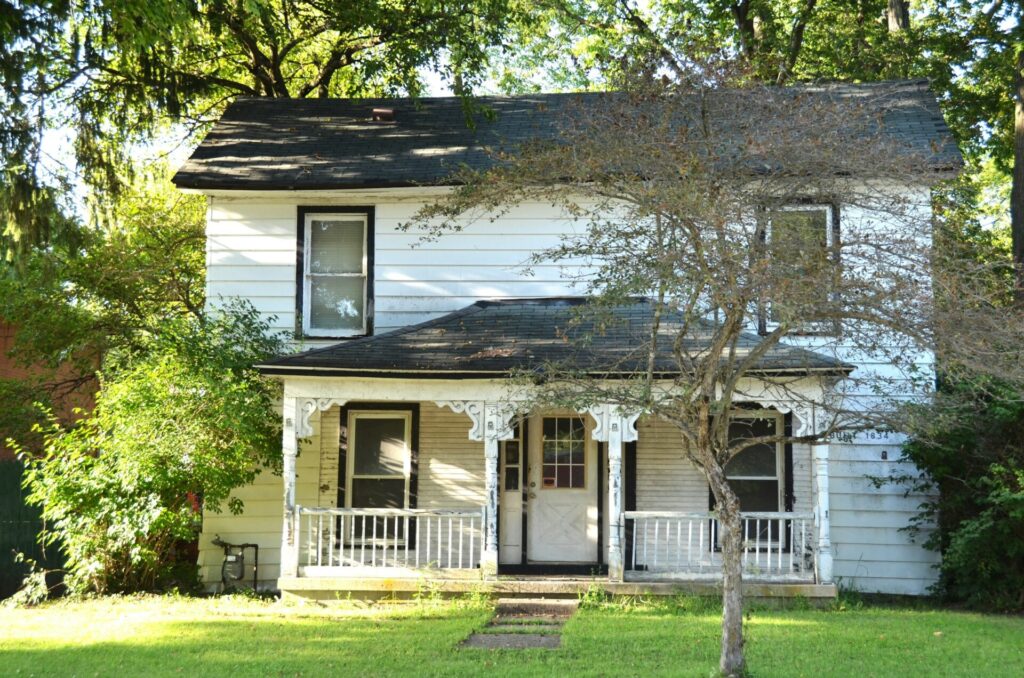
- Older homes that need work. Many have deferred maintenance, meaning years of skipped repairs to the roof, furnace, plumbing or wiring.
- Manufactured homes. Many sit on a leased lot in a manufactured home community. In that case, you pay lot rent on top of any loan payment.
- Foreclosures and HUD homes. Banks and HUD sell homes they took back after foreclosure. Learn how to find and buy a HUD home, and what a pre-foreclosed property is.
- Tax sales and auctions. Counties sell properties, or the tax liens on them, to collect unpaid property taxes. The rules vary widely by state.
How to search
- Set a $50,000 maximum price on the big listing sites and widen the search area. Filter out manufactured homes if you want only site-built houses.
- Check the HUD Home Store. You bid through a HUD-registered broker, and buyers who will live in the home get a priority period before investors can bid.
- Find your county’s tax sale list and read its rules before you register to bid.
What a $50,000 house usually comes with
A low price usually reflects the home’s condition, its location or both. Here is what to check before you make an offer.
Condition. Expect older roofs, heating and cooling systems, water heaters, plumbing and wiring. Also, a new roof or furnace does not cost less because the house was cheap.
Inspection. A professional home inspection is the best way to learn what you are buying. An appraisal does not replace it. For example, VA’s lender handbook notes that its appraisers do not test mechanical systems or appliances. Read more on why a home inspection matters.
Insurance. Get a quote before you make an offer. The National Association of Insurance Commissioners notes that older homes may not qualify for preferred programs, and insurers may require updated heating, plumbing, wiring and roofing.
Property taxes. Ask for the latest tax bill. However, it may change if the county reassesses the home after the sale.
Buying sight unseen. Buying from photos alone can hide a failing foundation, missing fixtures or code violations. If you can’t visit, hire a local inspector and agent to see the home for you.
Auctions and tax sales
Auction and tax sale homes are often sold as-is, and you may not be able to go inside before you bid. They can also come with title problems, such as unpaid liens. In some states, the former owner has a redemption period to pay the back taxes and reclaim the property. These rules vary by state, so check your state’s law and get a title search before you bid.
Can you get a mortgage for a $50,000 house?
Yes, but a small mortgage loan can be harder to find than a large one. In addition, the home has to meet the loan program’s property rules.
Some lenders set a minimum loan amount
A lender’s cost to make a loan is much the same at $48,000 as at $400,000, but it earns less on the small loan. As a result, some lenders set a minimum loan amount. Therefore, ask each lender about its minimum. The guide to small mortgage loans covers where to look.
Closing costs take a bigger bite
Many closing costs, such as the appraisal and credit report, don’t shrink with the loan. Say a buyer pays a hypothetical $3,000 in such fees. That is about 6.2% of a $48,250 loan, but only about 0.7% of a $402,887.50 loan. See how much closing costs are for the usual items.
The house must meet property standards
Each major loan type sets a minimum standard for the home:
- FHA: HUD’s Minimum Property Requirements call for a home that is safe, sound and secure (Handbook 4000.1).
- VA: VA’s Minimum Property Requirements aim for a home that is safe, structurally sound and sanitary.
- USDA: An existing home must meet HUD’s minimum property requirements (HB-1-3555, Chapter 12).
- Conventional: Fannie Mae requires repairs for deficiencies that affect safety, soundness or structural integrity. The lender must show they were fixed before it delivers the loan.
So a house with a bad roof, no working heat or a failing foundation may not qualify as-is. In that case, the seller would need to repair it first, or the buyer would need a renovation loan or cash.
Renovation loans can cover repairs
An FHA 203(k) loan combines the purchase price and repair costs in one mortgage. The Limited 203(k) covers up to $75,000 of minor, nonstructural repairs, according to HUD Mortgagee Letter 2024-13. The Standard 203(k) is for major rehabilitation and requires at least $5,000 in repairs, according to HUD’s 203(k) page.
On the conventional side, Fannie Mae’s HomeStyle Renovation mortgage also adds repair costs to the loan amount. Learn more about the FHA 203(k) loan and other fixer-upper loans.
Manufactured homes follow different rules
Financing depends on how the home is titled. Fannie Mae requires the home and the land to be legally classified as real property. In contrast, a home titled as personal property needs a different loan, which HUD notes has traditionally meant a comparatively high-interest, short-term installment loan.
FHA’s Title I program can insure a loan on a manufactured home titled either way, including one on a leased lot. For a leased lot, HUD requires an initial lease term of three years and at least 180 days’ notice before the lease ends. HUD Handbook 4000.1 (revised August 2026) lists Title I limits of $105,532 for a single-section home and $193,719 for a multi-section home. Title I also requires a cash investment of at least 5% of the price, and the home must be your principal residence. See FHA manufactured home loans for details.
USDA loans in rural areas
Many houses under $50,000 are in rural places, so a USDA guaranteed loan may fit. The home must be in a USDA-designated rural area, and household income can’t exceed the program’s moderate-income limit. Read more about USDA loans.
Cash and other options
- Cash. A cash buyer can close faster and can buy a home that doesn’t meet loan standards. Even so, get an inspection and title insurance.
- Personal loan. An unsecured loan has no property standards. However, rates are often higher and terms shorter than on a mortgage.
- Home equity loan on another property. This can fund a cash purchase, but your current home secures the debt.
- Seller financing. With a contract for deed, or land contract, you pay the seller in installments, and the seller keeps the deed until you finish paying.
The CFPB warns that under a contract for deed, the seller often tries to evict right away after a missed payment and may try to keep all the money and work you put in. Read the CFPB’s contract for deed guide and talk to a HUD-approved housing counselor before you sign. Rent-to-own is a related arrangement with its own pitfalls; see the dos and don’ts of rent-to-own.
What the payment on a $50,000 house can look like
The table compares an FHA loan on a $50,000 home with the same terms on the September 2026 NAR median price of $417,500. Both assume 3.5% down, a 30-year fixed rate, the 1.75% upfront mortgage insurance premium (MIP) financed into the loan, and annual MIP of 0.55%.
The 6.875% rate is only an example. Freddie Mac’s weekly survey put the average 30-year fixed rate at 7.11% on November 12, 2026, and your rate depends on your credit and lender. Check current mortgage rates for today’s numbers.
| FHA loan, 3.5% down, example 6.875% rate, 30 years | $50,000 home | $417,500 home |
|---|---|---|
| Down payment (3.5%) | $1,750 | $14,612.50 |
| Base loan | $48,250 | $402,887.50 |
| Upfront MIP (1.75%, financed) | $844.38 | $7,050.53 |
| Total loan | $49,094.38 | $409,938.03 |
| Principal and interest | $322.52 | $2,693.00 |
| Annual MIP (0.55%), per month | $22.11 | $184.66 |
| Monthly payment, before taxes and insurance | $344.63 | $2,877.66 |
These payments leave out property taxes and homeowners insurance. On a cheap house, those can be a large share of the total payment, so get real figures for both. With less than 10% down, FHA’s annual MIP lasts for the life of the loan. For how your income fits in, see how much house you can afford.
Because rates and fees vary by lender, especially on small loans, compare quotes from more than one lender.
Are houses under $50,000 a good idea?
They can be, for the right buyer and house. The upsides:
- A low monthly payment, or no payment at all if you buy with cash.
- A way to own a home without a large loan.
- A rental or fixer-upper project for a small investor.
The risks:
- Repairs can cost more than the purchase price.
- Resale can be slow, and prices may rise little in some low-cost areas.
- A home that doesn’t meet property standards can’t get most mortgages as-is. That also limits who can buy it from you later.
Before you make an offer, get an inspection and a contractor’s repair estimate. Then budget for repairs on top of the price, along with taxes and insurance. The first-time home buyer’s guide walks through the rest of the process.
FAQ about houses under $50,000
Can you buy a house for $50,000?
Yes. About 4.7% of owner-occupied homes were valued under $50,000 in the 2025 ACS. Most homes for sale at that price are in rural areas and older cities, and many need repairs.
Where can I buy a house for $50K?
Look in small towns, rural counties and some older industrial cities. In the 2025 ACS, Mississippi and West Virginia had the highest shares of homes valued under $50,000. To search, use listing sites with a $50,000 price cap, the HUD Home Store and county tax sale lists.
Can you get a mortgage for a $50,000 house?
Often, yes, if the home meets the loan program’s property standards and you find a lender that makes small loans. However, a house in poor condition may need a renovation loan, such as an FHA 203(k), or cash.
Are there houses under $50,000 in Texas?
Yes. In the 2025 ACS, about 379,000 owner-occupied homes in Texas were valued under $50,000. Listings at this price turn up in some rural areas and smaller cities. Use a listing site’s price filter to see what is for sale now.
Is a $50K house worth it?
It can be, if repairs, taxes and insurance still fit your budget. Get an inspection and a repair estimate first. Also, check that the home qualifies for financing, because that affects any future sale too.
Next steps for buying a $50K house
Houses under $50,000 are real, but the price is only the starting point. Repairs, taxes, insurance and closing costs all add to it.
Before you make an offer, make two calls. Ask a lender whether it makes loans at your price and which programs fit the home. Then get an inspection and a repair estimate, so you know the full cost before you commit.